

Tom Hofstedter gets $23.02 in assets. Trustees and executives get $12.01 in cash. Public holders get $10.14 in GO+cash
I will present another article with a proforma valuation of Lantower REIT assuming the GO/CRAL deal does not proceed.
Bad Process
Multiple parties conducted serious negotiations in 2025:
From 2024 through September 2025 a private equity firm “Company A” offered several possible transaction structures for a cash acquisition of part or all of H&R.
In February 2025 Blackstone submitted a preliminary cash offer for all of H&R.
In May 2025 a Canadian private equity firm “Company B” submitted an unsolicited cash offer with a US-based multifamily real estate partner “Company C”.
H&R considered sale of a majority of its assets, but “the Independent Trustees determined to reject an option that would result in H&R REIT retaining less desirable assets as a public company undergoing liquidation, given the risks inherent in such proposal and the likelihood of diminished value for H&R REIT Unitholders”. No further explanation of these risks and the estimated value that could have been realized for H&R holders is provided.
Once the Strategic Review process concluded, Tom Hofstedter was granted permission to negotiate a transaction with GO on his own. No alternatives were considered. Aside from the spreadsheet valuation models prepared by CIBC and NBCCM, no consideration was given to the suitability of GO Residential as a merger partner.
No assessment of GO governance and fraud concerns
No assessment of GO management, their very limited experience with Class A institutional quality real estate, their legal issues and possible conflicts of interest with their other businesses, their very limited experience as public company executives, and their track record of extremely poor returns for investors in the GO Partners LLCs and GO Residential REIT.
No consideration of the low liquidity in GO equity and the impact on the purported merger value of the heavy dilution that would result from the issuance of 134mm new units (compared to the existing balance of only 37mm publicly tradable units).
Hofstedter Gets $23.02/unit
The circular contains a highly misleading presentation of the asset exchange with the Hofstedter syndicate (CRAL)
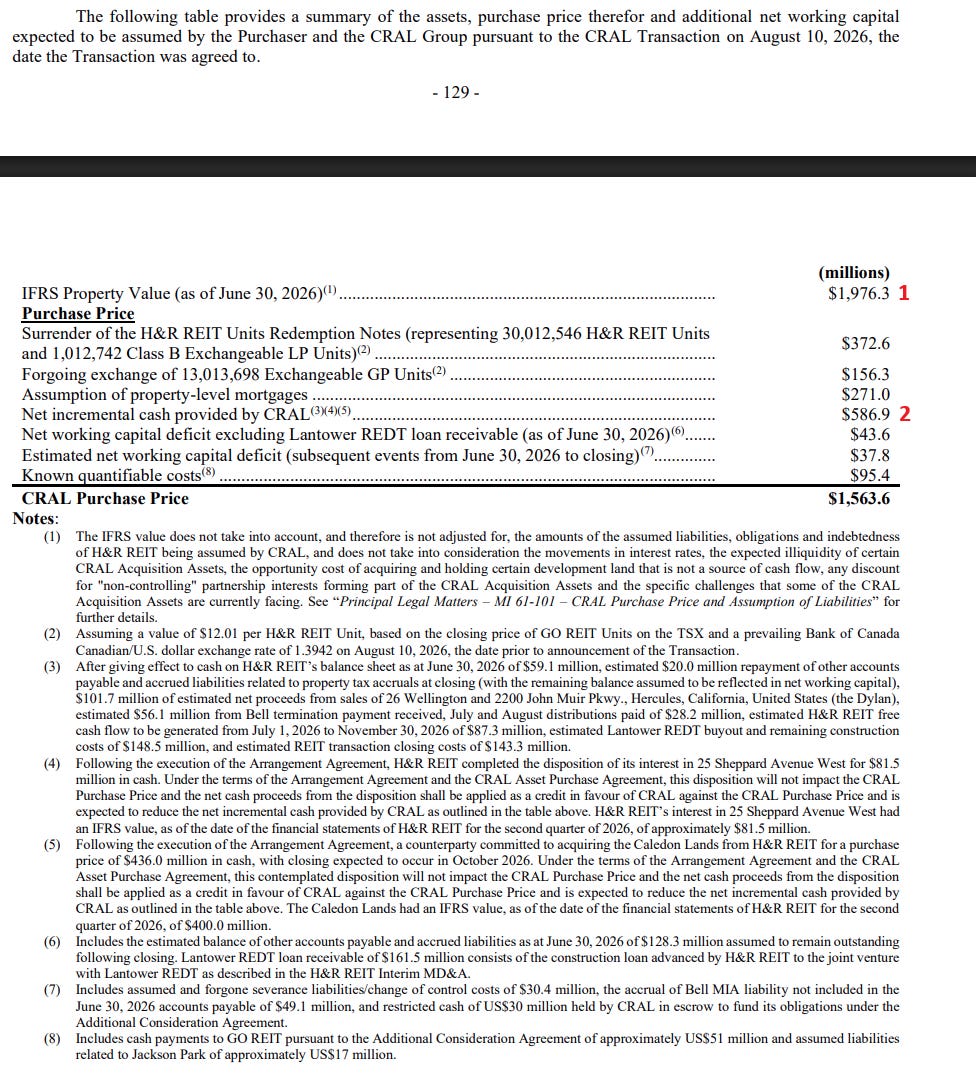
This includes $551mm IFRS value of properties that will be sold before closing of the deal (footnotes 3,4, and 5)
The “Cash provided by CRAL” is entirely cash retained by H&R prior to closing from asset sales and even suspended dividends. That’s right, our dividends are shown in the table as a cash contribution from Tom!
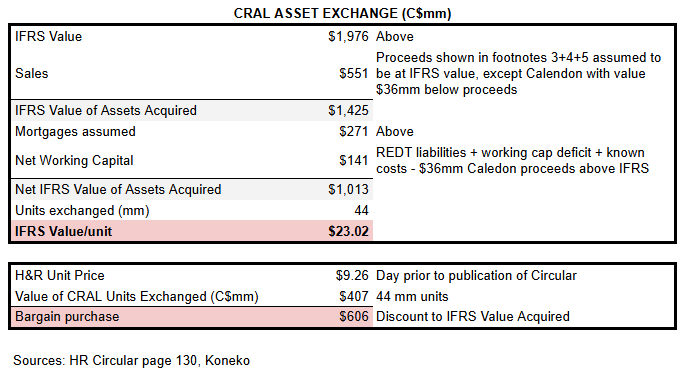
Using the entries in the table shows the CRAL value received per unit exchanged is $23.02, very close to the $22.47 that I estimated on 8/17.
Public Gets C$10.14 And A Huge Tax Liability
H&R described the CRAL deal as “a critical component that enabled the en bloc transaction to proceed”, but isn’t it more likely that the opposite was true? Hofstedter believed the GO deal would enable him to extract $606mm of unitholder equity for himself.

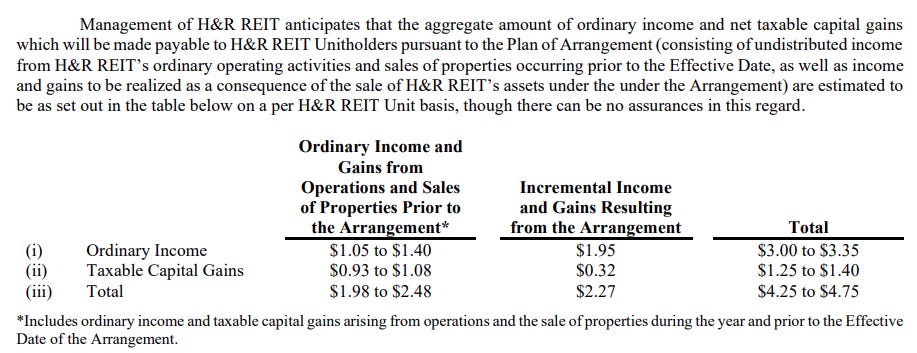
The timing of the proposed asset sales is structured so that all of the taxable gain from the Crestpoint, Blackstone, and Caledon sales will be conveyed to public holders. The estimated taxable income will probably exceed the C$4.28 cash distribution.
Conflict of Interest
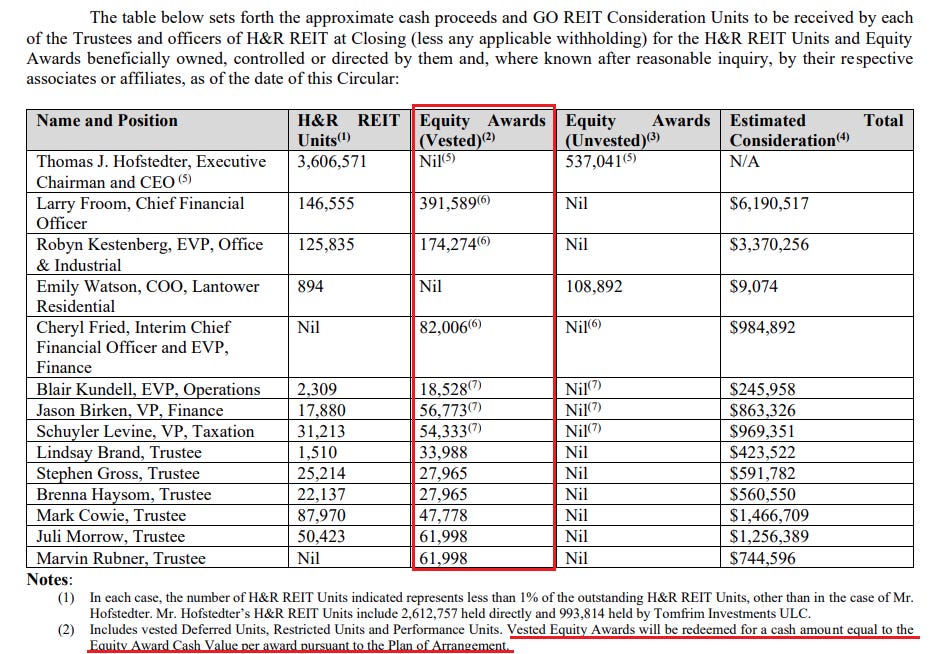
The Board of Trustees that approved the transaction and executives that signed voting support agreements will receive immediate vesting of all outstanding equity awards and exchange them for $12.5mm in cash, based on a predetermined “Equity Award Cash Value” of $12.01.

Disclosures & Notes
At the time of publication the author held units of H&R REIT and no position in units of GO Residential. This disclosure should not be interpreted as a recommendation to make any transaction in any security. Investors are encouraged to check all of the key facts cited here from SEDAR filings and other sources prior to making any investment decisions. The author believes all information in the article is accurate as of the date of publication.
A copy of this article was sent to H&R REIT at the time of publication. If the company can identify any factual errors using information that was public at the time of release then corrections will be made as promptly as possible.
I believe this article serves the public interest so it has been published with no paywall. Please share with anybody who might be interested.