

Prices of real estate and finance securities have suffered from the recent jump in interest rates. Borrowing costs have risen and the discounted value of future cash flows has fallen.
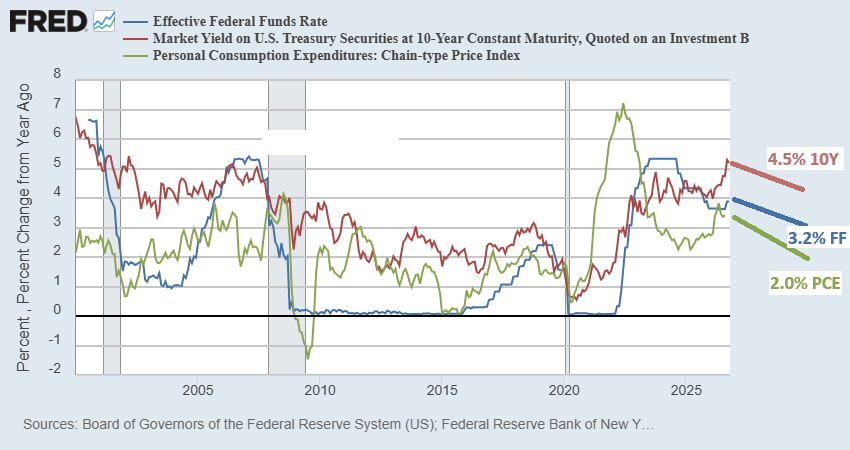
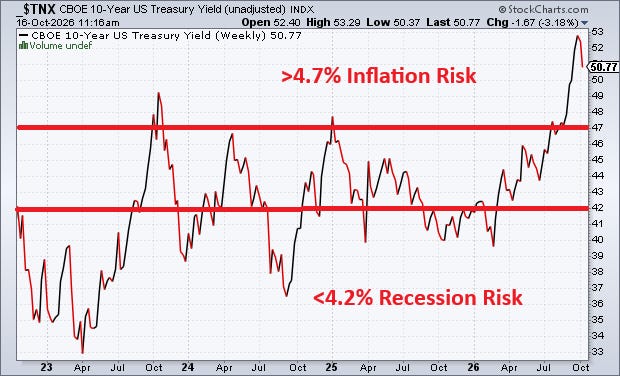
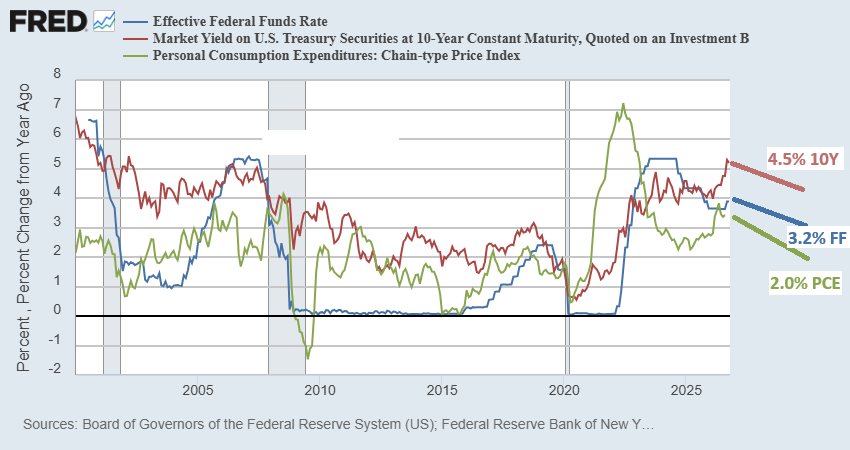
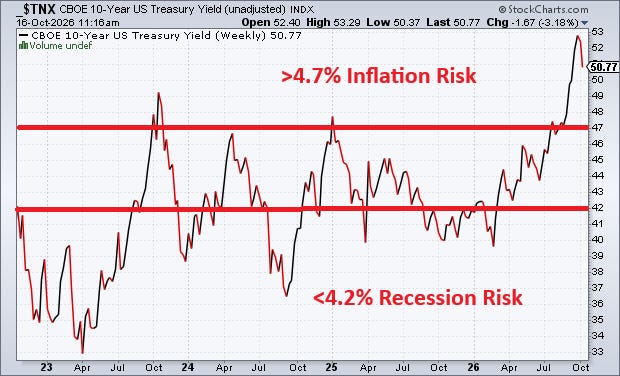
The equilibrium yield on 10-year treasury bonds should be a term premium of 100-150bp over the neutral Fed Funds rate. The median Fed member projection of the long-term fed funds rate consistent with a 2.0% inflation rate has risen to 3.2%. That implies an equilibrium bond yield of 4.20-4.70%.
The recent surge in treasury yields signals lack of confidence that the Fed will be successful in curbing inflation.
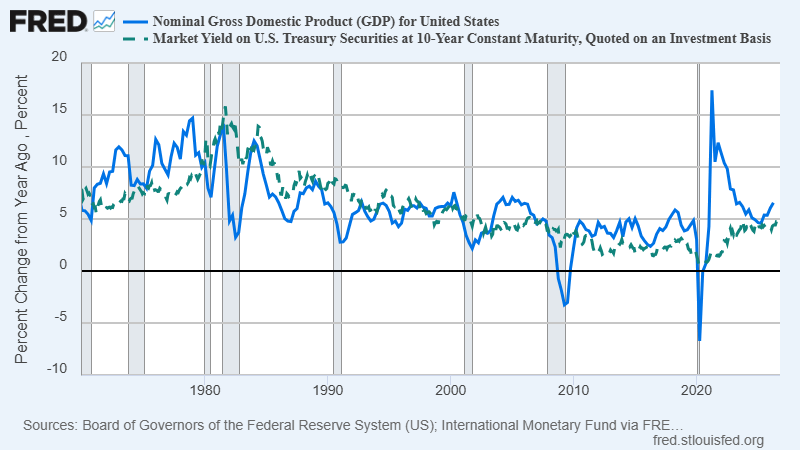
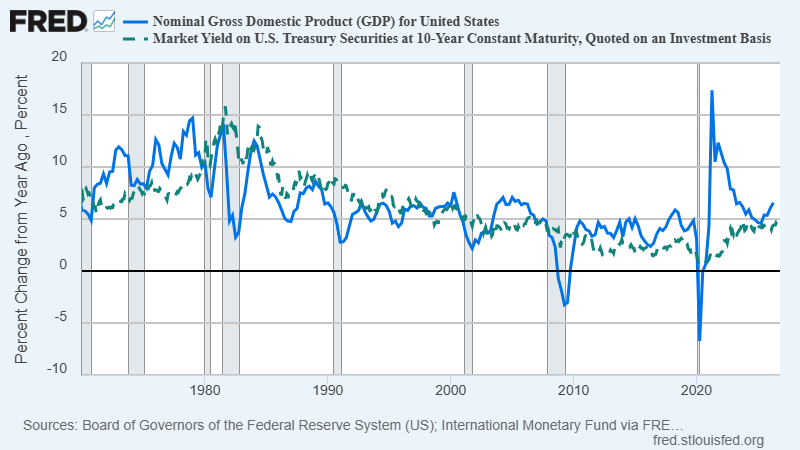
Long-term treasury yields have a strong correlation with nominal GDP growth. If inflation is 2.0% and potential growth is 2.5% then bond yields should gravitate towards 4.5%. Growth in recent quarters has been much higher (6.56% in 2Q26), but that is very likely to be unsustainable. The economy has been boosted by massive AI capex and AI-related wealth effects, but has not yet shown any increase in productivity that would provide confidence in higher long-term growth potential.
In the medium term rates should be lower and supportive of a rebound in asset values. Companies with high near-term debt maturities, or business plans that require near-term asset sales, are at risk.
Latest perspectives:
Star Holdings (STHO)
Rithm Property trust (RPT)
Elme Communities (ELME)
Redwood Trust (RWT)
Noah Holdings (NOAH)
Undisclosed
Undisclosed