

Canadian Real Estate has delivered a +3.7% ytd total return (XRE a/o 9/22). US REITs are +6.9%, and the CAD is -2.2% vs USD.
REITs and interest-sensitive equities have been weak, but I see these potential catalysts in coming months:
Iran Truce because the global economic cost is so high. Trump always threatens the worst right before giving up. This will relieve inflation pressure which will relieve interest rate pressure.
Trade Truce because TACO.
US fiscal consolidation following the midterm election. This will relieve inflation pressure which will relieve interest rate pressure. Of course there will be conflict, drama, and periodic US government shutdowns.
Building Canada Strong domestic investment program will lead to optimism about construction demand and industrial production in the near-term and productivity in the medium term.
Topics:
Sector Overview
Valuation Comparison ($)
Canadian Trade Ideas Update ($)
Noteworthy Insider Activity ($)
Sector Overview:
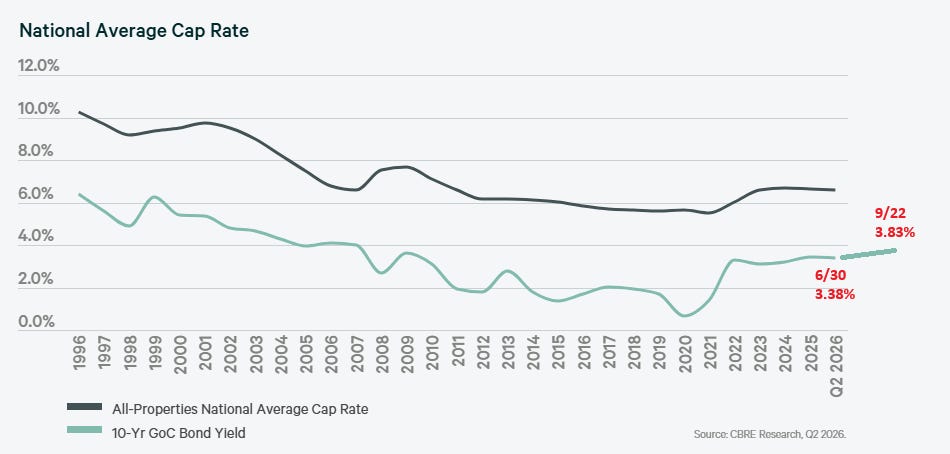
The yield premium of real estate cap rates over 10-year bond yields is under pressure due to the sharp qtd rise in bond yields. Choice Properties, one of the safest REITs, just issued 7-year debentures at 4.84%.
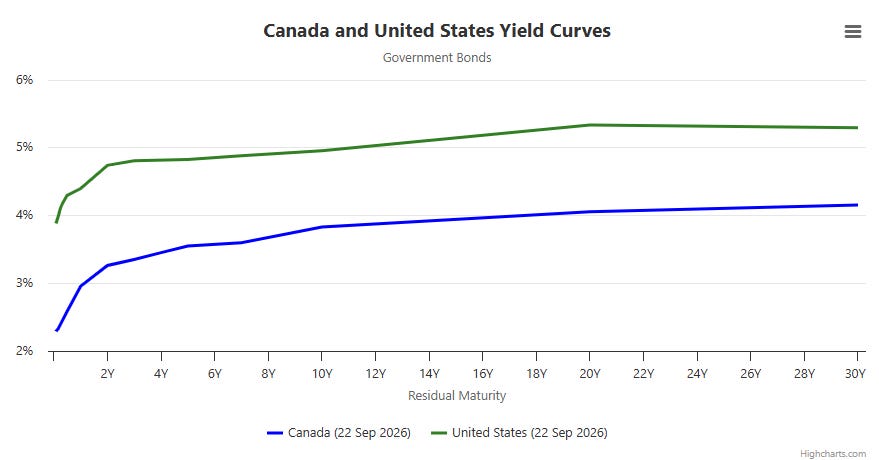
Canadian yields are still at least 110bp lower than the US at every maturity. For real estate investors, Canadian property offers a positive return over financing cost, but US property buyers may get little or even negative return on leverage.
Insiders at 22 of 34 REIT/REOCs were buyers since 1/1/26 and 7 had net insider sales. REIT/REOCs have repurchased $569mm of equity since 1/1 (reported to 9/22) with the largest buybacks at Boardwalk (7.7% of market cap), Clarke (3.8%), Dream Industrial (2.6% of market cap), and Killam (3.4%).